 Arthya
On 16 October the Reserve Bank approved a branch amalgamation. It did not set a card rate.
21 October 2026
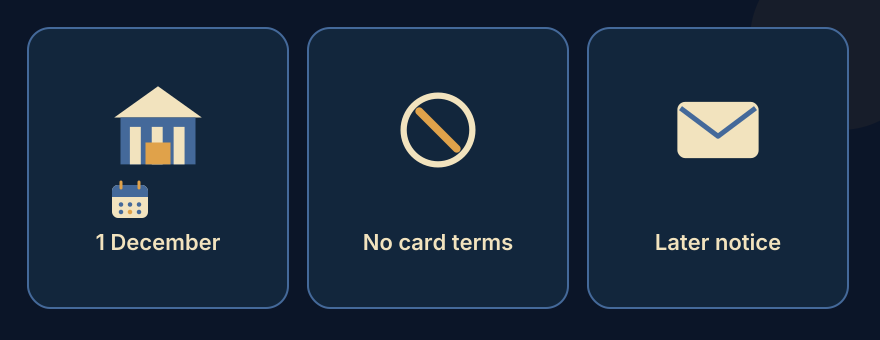
On 16 October 2026 the Reserve Bank of India published a press release. It has sanctioned the scheme of amalgamation of the Indian branches of Emirates NBD Bank P.J.S.C., the transferor bank, with RBL Bank Limited, the transferee bank. The sanction is under sub-section (4) of Section 44A of the Banking Regulation Act, 1949. The effective date in the release is 1 December 2026. From that date, the release says, all the Indian branches of Emirates NBD Bank P.J.S.C. will function as branches of RBL Bank Limited. The release number is 2026-2027/1342.
The same day, RBL Bank filed a disclosure with the stock exchanges. The letter is dated 16 October 2026 and is signed by Niti Arya, Company Secretary. It says the bank received an approval letter of that date from the Reserve Bank, sanctioning the amalgamation under the same sub-section, as per the terms mentioned in that approval letter. It repeats the effective date. It repeats that the Indian branches will function as branches of the bank from 1 December 2026. The letter says the filing is hosted on the bank’s own website. On the date and on the branches, the press release and the bank’s letter say the same thing.
The bank’s letter points to further terms inside the Reserve Bank’s approval letter. Those further terms are not restated in the public press release. This article uses the two public texts. It does not fill in clauses they do not contain.
What the two texts do not say
The absence is the part a cardholder needs. Neither text names a credit card. Neither names a reward point, an annual fee, a finance charge, a cash-advance fee, or a credit limit. Neither tells a customer to close an account, replace a card, or change a standing instruction before December. Silence is not a promise that a card stays as it is. Silence is also not a new rate.
If you bank at an Emirates NBD branch in India, the release is about that branch. From 1 December 2026 it is to function as a branch of RBL Bank. The release does not list the cities, and this page will not add a list. If you hold a credit card issued by RBL Bank, the same texts do not announce a new fee or a new earn rate on that card. A card from any other issuer sits outside the release.
Where a card change would show up
A change to a card lives in a different Reserve Bank document. For a card issued by a commercial bank, that document is the Reserve Bank of India (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025, updated as on 1 October 2026. Three passages sit beside any later letter. If a sentence here and the PDF seem to differ, use the PDF.
Paragraph 79 says the terms may be altered by the card-issuer, but 30 days’ notice of the change shall be given to the cardholder so that he or she can withdraw if he or she so chooses. After that notice period, a cardholder who has not withdrawn is treated as having accepted the terms. The change shall be notified through all the communication channels available.
Paragraph 34 is in the same directions. It says card-issuers shall not unilaterally upgrade credit cards and enhance credit limits. It says explicit consent of the cardholder shall be taken whenever there is any change in terms and conditions. A reduction in the credit limit is to be intimated to the cardholder. Paragraph 79 and paragraph 34 sit in one PDF. This article does not choose between them.
Paragraph 23(7) is about charges. Changes in charges shall be made only with prospective effect, with prior notice of at least one month. If a cardholder wants to surrender the card because a charge has changed to their disadvantage, the directions say the issuer shall permit that closure without an extra charge for the closure itself, subject to payment of all dues by the cardholder.
Paragraph 91 says the issuer shall give the cardholder a term-sheet of the Most Important Terms and Conditions. Fees, drawal limits, and billing are on that list. A way to read one sheet in a sitting is in how to read your card’s benefits and the MITC. The policy rate, and the merchant charge still waiting on a date after Diwali, are separate articles: the repo rate moved on 7 October, and the UPI merchant charge is waiting until after Diwali.
What to do with 1 December
Treat 1 December 2026 as the date the release gives for the branches. It is not, on its own, a due date on a statement, and it is not the day a reward programme ends. Until a notice from your own issuer mentions this amalgamation, the card sheet you already hold is still the sheet that describes that card.
If a notice does arrive, set it next to the sheet you hold now. Compare the annual fee, the reward or cashback line, including any excluded category, and the interest on a balance you carry. The 16 October approval does not make that comparison, and it does not rank one card against another.
The check for this week is small. Open the issuer’s app, or the last terms email, and see whether anything dated after 16 October 2026 mentions the amalgamation. No such notice means the current sheet is still the sheet. A notice means the new letter and the old sheet should be read together, with the directions above, before you treat a benefit as changed. The branch date and the card sheet remain two papers.
Sources
Disclaimer
This article is for general information only. It is not financial, legal, or tax advice, and it is not a recommendation to apply for, keep, or close any card. Card benefits, fees, and terms are set by the issuer and the card network, and they change often. Verify them with your bank, and read your own Most Important Terms and Conditions, before you rely on them. Arthya is not affiliated with or endorsed by any bank or card network. All trademarks belong to their owners.